This article may contain affiliate links.
Electrifying a commercial fleet can reduce fuel use and change long-term maintenance costs, but the financial case depends heavily on how vehicles and charging infrastructure are funded.
A fleet that focuses only on purchase price can underestimate interest, installation costs, utility upgrades, vehicle downtime and the timing of expected operating savings. Before ordering vehicles, operators need a financing model that reflects the entire deployment rather than the cost of the EVs alone.
1. Calculate the Full Amount Being Financed
Start with every capital expense required to put the vehicles into service. The vehicle purchase price is only one component. Depending on the fleet, the project may also require chargers, electrical upgrades, trenching, networking equipment, engineering, permits, software and installation labor.
Some costs may be paid in cash while others are financed. Separate them clearly so the business knows exactly how much debt is being used for the project.
2. Track Interest as It Is Incurred
Financing costs should be modeled over the entire loan term, not treated as an afterthought. Finance teams need to understand how much principal remains outstanding, the applicable interest rate, payment frequency, and any variable-rate provisions.
Accounting teams should also properly track interest accrued between contractual payment dates so financial reports reflect borrowing costs in the appropriate reporting period. This becomes particularly important when a fleet uses several loans or financing agreements with different rates and payment schedules.
3. Compare Financing Against Total Cost of Ownership
A lower monthly payment does not necessarily mean a lower-cost fleet. Extend the analysis across the expected ownership period. Include acquisition price, financing, electricity, maintenance, insurance, tires, charging infrastructure, taxes, fees, expected downtime and eventual resale value.
The U.S. Department of Energy’s Alternative Fuels Data Center guidance for electric fleets recommends looking at both upfront and ongoing costs when building an EV fleet budget. A total cost of ownership model provides a better basis for comparing an EV with a gasoline or diesel vehicle performing the same duty cycle.
4. Match Loan Terms to Vehicle Life
Longer financing terms reduce monthly payments but increase the period over which interest is paid. They can also create problems if the loan remains outstanding when the vehicle is ready for replacement. Estimate the practical service life of each vehicle type.
A local delivery van running predictable daily mileage may have a different replacement cycle from a heavy-duty truck operating multiple shifts. The financing term should make sense relative to expected vehicle use, depreciation, warranty coverage and replacement plans.
5. Finance Charging Infrastructure Separately Where Useful
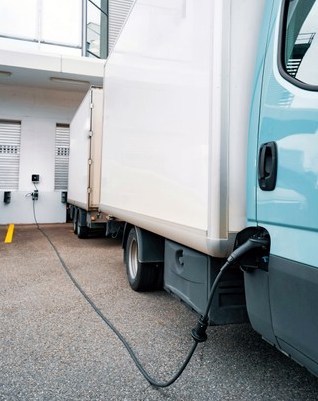
Vehicles and charging equipment do not always need the same financing structure. A vehicle may be replaced after several years, while electrical infrastructure could remain useful across multiple generations of EVs.
Separating these assets can make the financial model clearer.
Charging Costs May Include
- Charging hardware
- Electrical panels
- Transformers
- Trenching and conduit
- Network subscriptions
- Permitting
- Engineering
- Installation labor
- Future capacity upgrades
DOE fleet guidance also notes that installation costs can vary considerably according to equipment type, site conditions, electrical upgrades and permitting requirements.
6. Model Utility Costs Before Buying Vehicles
Electricity costs need to be estimated from actual operating patterns. Start with daily vehicle mileage, energy efficiency, charging location, available dwell time, and electricity rates. Then determine when vehicles will charge.
If every vehicle returns at 5 p.m. and begins charging immediately, simultaneous demand may increase electricity costs or require greater electrical capacity. Managed charging can stagger charging events and move energy consumption into more favorable periods where the applicable utility tariff allows it.
The Department of Energy notes that managed charging can help fleets control energy-related operating costs and reduce pressure on electrical infrastructure.
7. Protect Cash Flow with Phased Deployment
Replacing an entire fleet at once concentrates financial risk. A phased rollout gives the company time to test assumptions before committing more capital.
Start with routes that have predictable mileage, reliable overnight parking and enough dwell time for charging. Track actual operating results. Compare electricity consumption, maintenance spending, driver hours, vehicle availability and route completion against the original financial model.
Those numbers can then improve financing decisions for the next group of vehicles.
8. Include Incentives Conservatively
Federal, state, local, and utility incentives can improve the economics of fleet electrification, but they should not automatically be treated as guaranteed cash. Verify eligibility, application deadlines, vehicle requirements, and payment timing.
An incentive received months after vehicle delivery does not solve an immediate cash-flow requirement. Build at least two scenarios. One should include expected incentives, while another should show whether the project remains financially manageable if funding is delayed or reduced. This prevents a financing plan from depending completely on money that has not yet been received.
9. Control Facility Operating Costs
Fleet electrification may also change how depots, service areas, parking facilities and customer-facing vehicle locations are operated. Charging areas need clear access, routine inspections and maintenance procedures. Additional equipment can also increase facility-management requirements.
Organizations operating dealer or customer-facing vehicle facilities can use a structured dealership cleaning checklist to define inspection standards for showrooms, service reception areas, customer spaces and workshop-adjacent areas. These expenses may appear minor compared with vehicle financing, but recurring facility costs belong in the operating budget if they are necessary to support the fleet.
10. Watch Residual Value Assumptions
Residual value can materially change a fleet financing model. A high projected resale value makes the long-term cost appear lower, but future EV values can be affected by mileage, battery condition, technology changes, market demand and new-vehicle pricing.
Use conservative resale assumptions. Run sensitivity tests showing what happens if actual disposal value is 10%, 20% or 30% below the original estimate. For leased vehicles, review mileage restrictions, end-of-term condition requirements and residual-value responsibilities carefully.
11. Measure Cost Per Productive Mile
Monthly loan payments alone do not show whether an EV deployment is financially successful. Measure the cost of putting vehicles to productive use.
Track Metrics Such As
- Financing cost per vehicle
- Energy cost per mile
- Maintenance cost per mile
- Charging infrastructure cost per vehicle
- Vehicle utilization
- Downtime
- Cost per completed route
- Total cost per productive mile
Compare these figures with the vehicles the EVs replaced. A vehicle with a higher acquisition cost may still perform well financially if it delivers enough productive mileage with lower operating costs.
12. Update the Financing Model with Real Data
The original business case should not disappear after the vehicles arrive. Replace estimated electricity consumption with actual charging data. Update maintenance assumptions when service records become available. Compare expected mileage with real utilization.
If vehicles are traveling far fewer miles than planned, the fleet may not be generating enough operating savings to justify the additional capital cost. Likewise, unexpectedly high charger utilization could support expanding the EV fleet without equivalent investment in new charging equipment.
Manage EV Financing as a Fleet System
Commercial EV financing is not simply about finding the lowest loan rate. Fleet operators need to manage vehicle acquisition, borrowing costs, charging infrastructure, electricity, incentives, utilization, maintenance, depreciation and residual value as one connected financial model.
Start with total cost of ownership, structure financing around realistic asset lives, and introduce vehicles in stages where possible. Most importantly, compare the original assumptions with actual fleet data.
A commercial EV program becomes financially stronger when operators know exactly where capital is going, how much that capital costs and whether each vehicle is producing enough operational value to justify the investment.
